Department Leadership
What will it take to perform the work?
See the labor, support, production, materials, and indirect resources the plan is expected to consume.
Forecast labor, fringe, indirect costs, G&A, support, materials, subcontractors, and project costs before the budget is committed.
BreakEven+™ helps a municipality build the cost structure behind a proposed budget—before the work begins and before the number becomes just another line item.
See the labor, support, production, materials, and indirect resources the plan is expected to consume.
Trace the budget back to wages, productive hours, indirect pools, support labor, and project assumptions.
Present a clearer explanation of the resources behind the number without exposing unnecessary employee-level detail.
Local government work is labor-intensive even when the public only sees the finished road, repaired water main, treatment process, fleet repair, concrete project, or maintained facility. Behind that work are wages, payroll-related burden, fringe, supervision, administration, facilities, equipment support, insurance, information systems, procurement, and other costs that may be shared across departments or programs.
BreakEven+™ is designed to organize those financial inputs into a forward-looking cost model. Instead of beginning with a project total and working backward, a municipality can establish the cost structure first, forecast the labor required to support it, and then carry those assumptions into estimates and internal planning. That is especially valuable when a city, village, town, county, district, authority, or publicly operated utility has its own employees performing direct work.
The objective is not to replace a municipality's accounting system, ERP, or adopted budget process. BreakEven+™ adds a cost-intelligence layer for planning. It helps teams examine what labor is expected to cost, what indirect resources support that labor, how shared pools are allocated, and what a proposed project or operating plan may need to recover.
The same reporting framework can support different municipal operating structures because the model starts with the entity's own labor, budgets, indirect pools, allocation assumptions, and project inputs.
Each page below focuses on the labor, indirect costs, support resources, materials, and project inputs that matter to that municipal operation.
Treatment, collection, maintenance, plant labor, support costs, rehabilitation, and utility budget forecasting.
Internal crews, support labor, materials, self-performed work, departmental overhead, and annual public works budgets.
Paving, patching, striping, street repair, production assumptions, crew hours, materials, and road-program budgets.
Storm sewers, culverts, catch basins, drainage maintenance, flood-control work, crews, materials, and capital improvements.
Collection labor, landfill and transfer operations, fleet support, disposal inputs, indirect costs, and sanitation budgets.
Internal municipal labor, engineering, inspection, materials, contractors, subcontractors, and infrastructure project budgets.
Grounds crews, facilities, shelters, playground maintenance, seasonal work, repairs, and parks operating budgets.
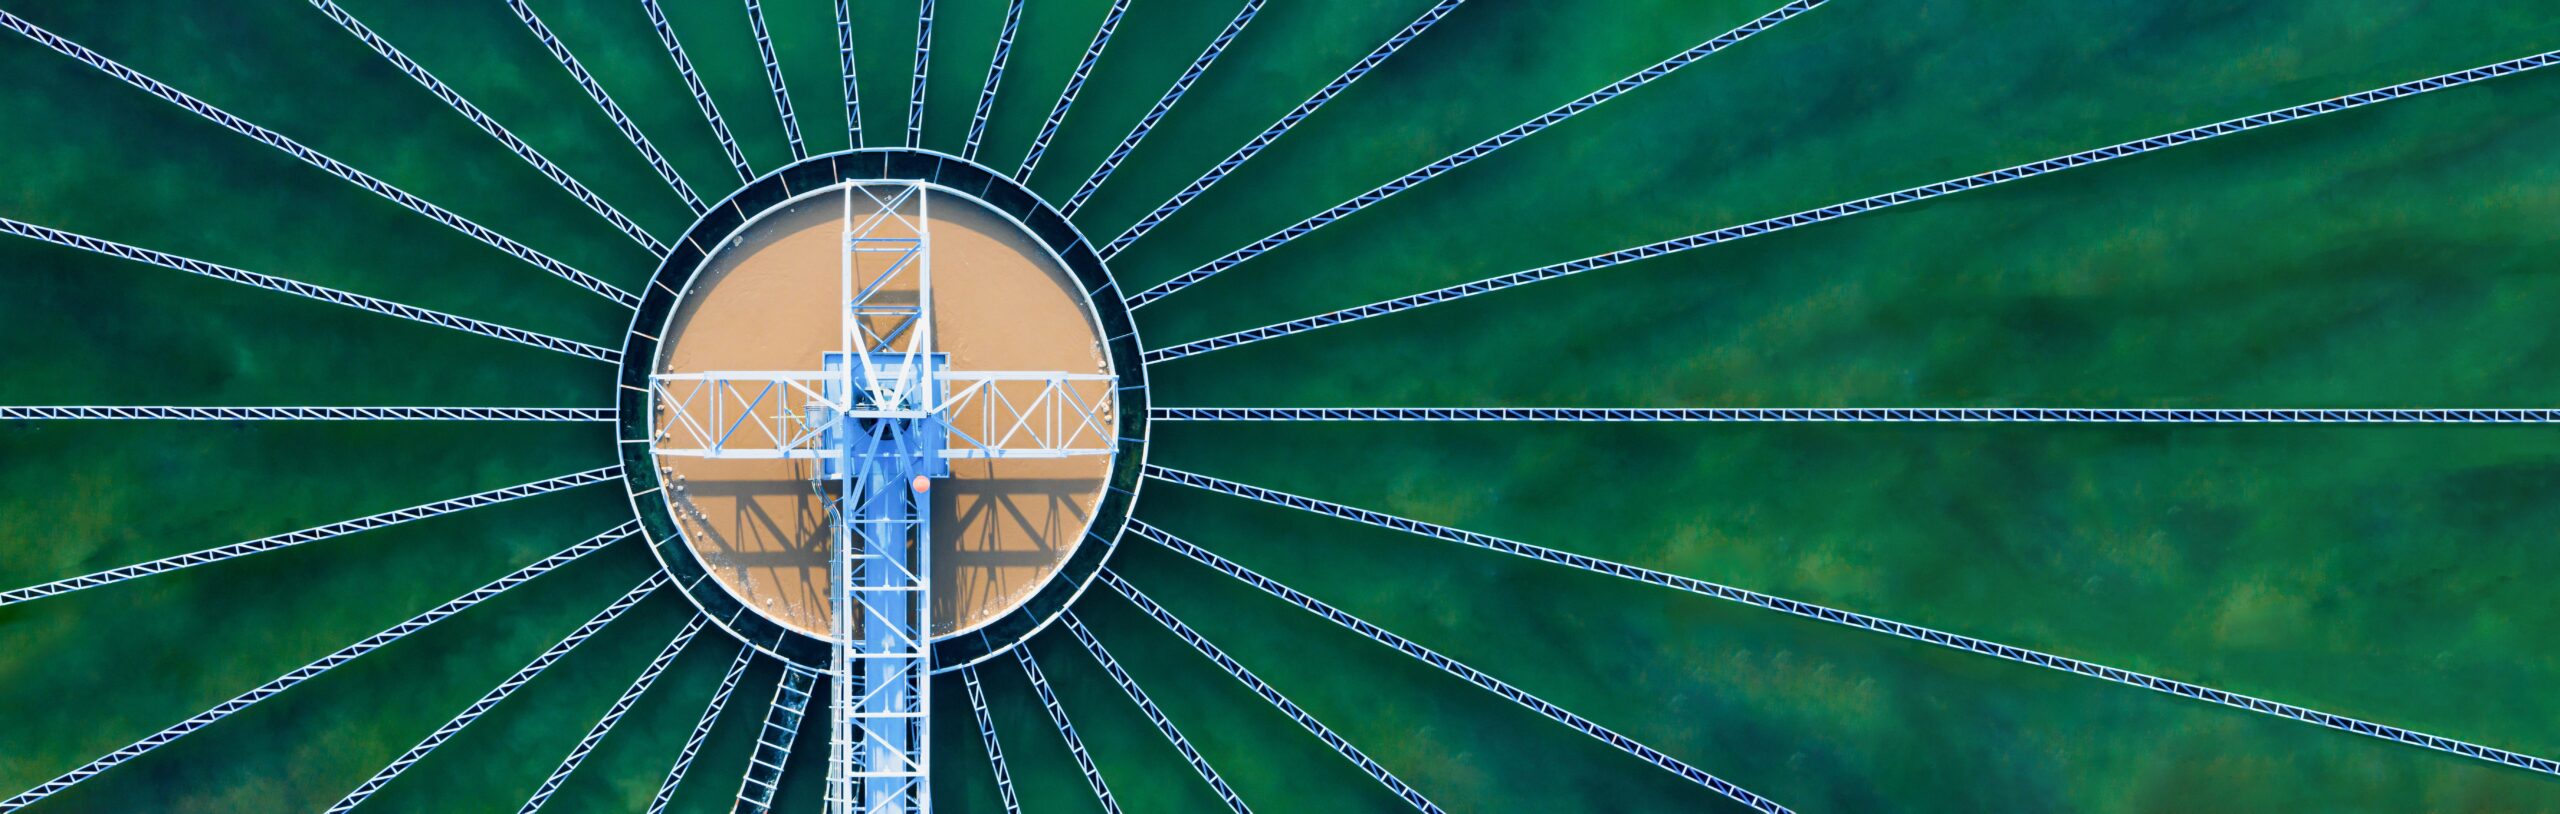
Treatment facilities are not only equipment and chemistry. They are also operators, maintenance personnel, electricians, mechanics, supervisors, laboratory support, administration, procurement, and capital work. When those people are employees of the municipality or utility, their direct and indirect costs can be modeled before annual budgets or project estimates are finalized.
FALIB® can help a utility establish a forecast labor foundation, distinguish direct activity from supporting costs, and examine how overhead or broader administrative pools affect the full cost picture. That can provide management with a more structured view when evaluating operating plans, maintenance programs, rehabilitation work, or internally performed project labor.
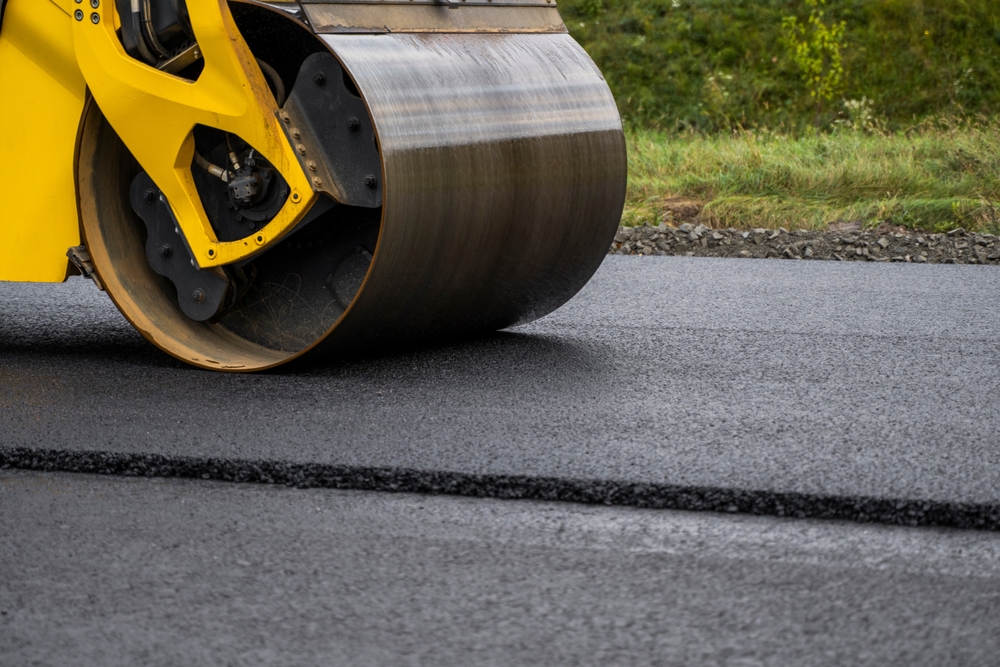
A road crew's hourly wage is only one part of the financial requirement behind the work. Public works may also carry foremen, supervisors, engineering support, facilities, dispatch, training, safety, administrative functions, and other indirect costs. BreakEven+™ lets a department model that structure explicitly instead of relying only on a wage rate or a historical average.
For self-performed paving, patching, concrete, signs, drainage, repair, or seasonal programs, the municipality can model productive labor hours and supporting costs before assigning a project value. The result is a stronger forecast for budgeting and a clearer internal view of the resources consumed by the work.
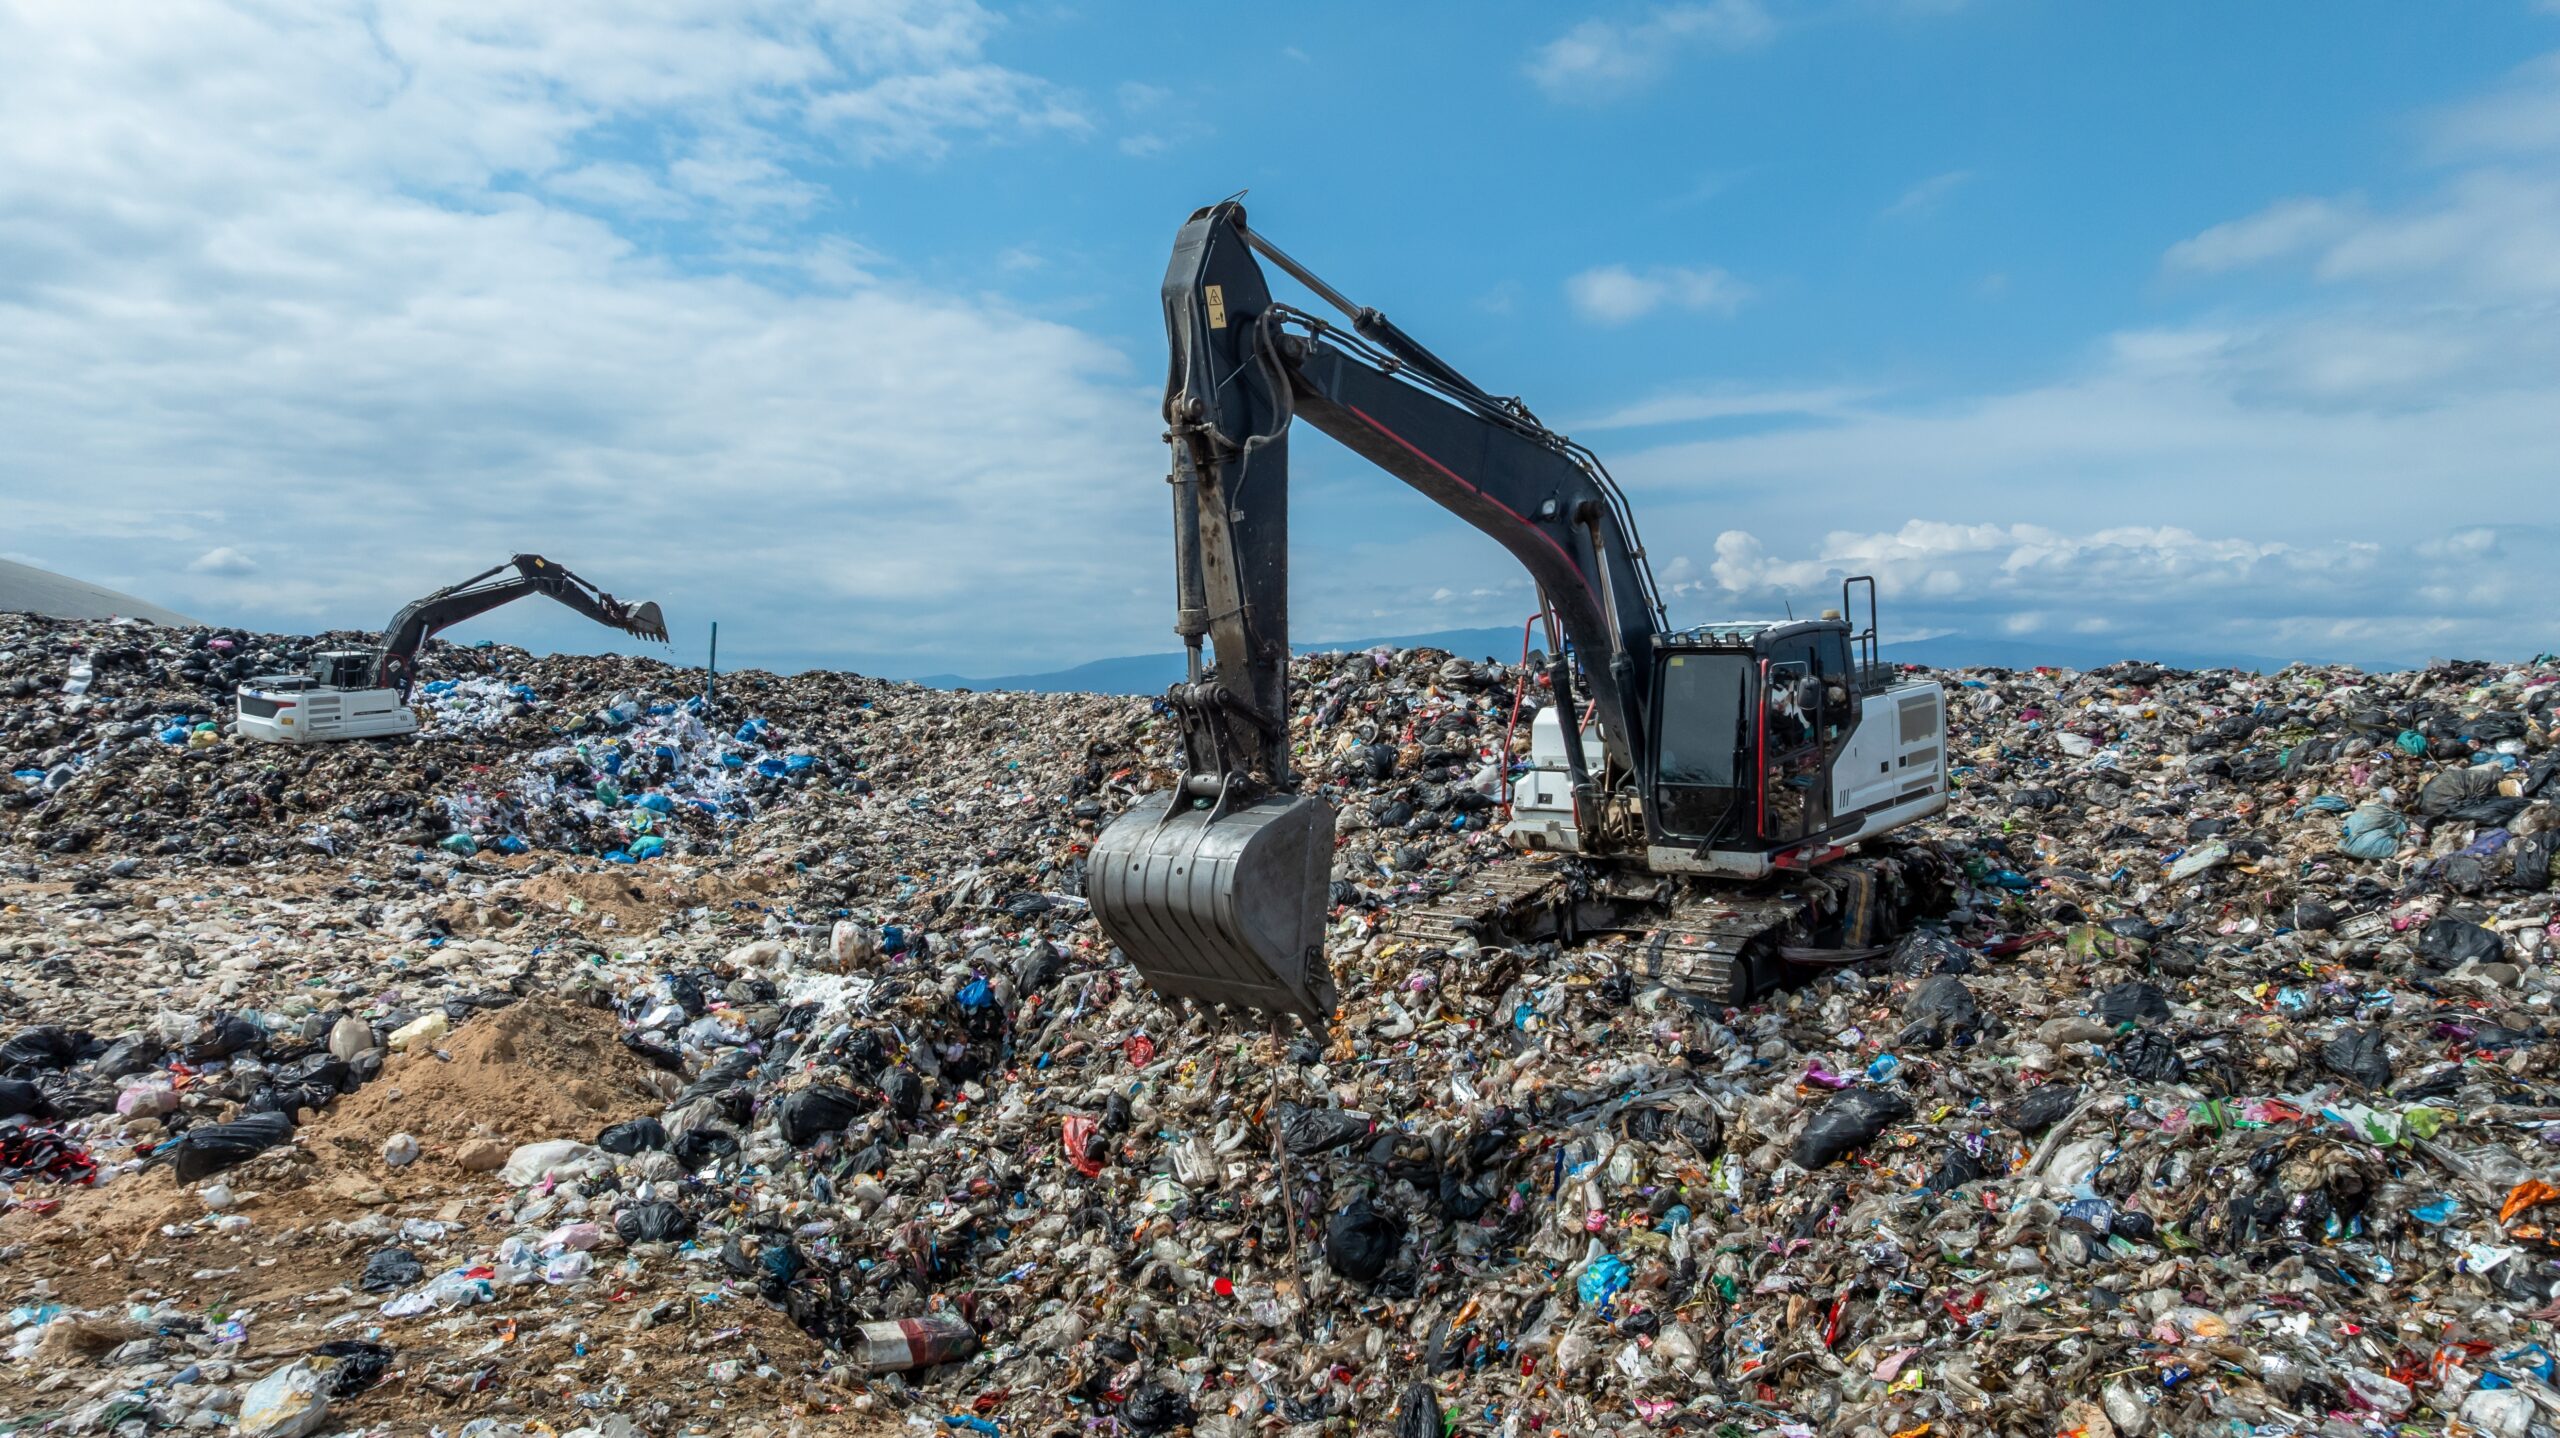
Labor-intensive public services can carry substantial operating support beyond the frontline employee. Solid waste and sanitation operations may include drivers, equipment operators, mechanics, supervisors, dispatch, administration, facilities, and outside services. A structured forecast helps explain how those layers contribute to the overall cost of delivering the service.
BreakEven+™ can be configured around a municipality's operating assumptions so management can test productive hours, labor mix, pool size, and cost allocation before relying on the output for planning. It is a forward model: change the assumptions, and the financial view changes with them.
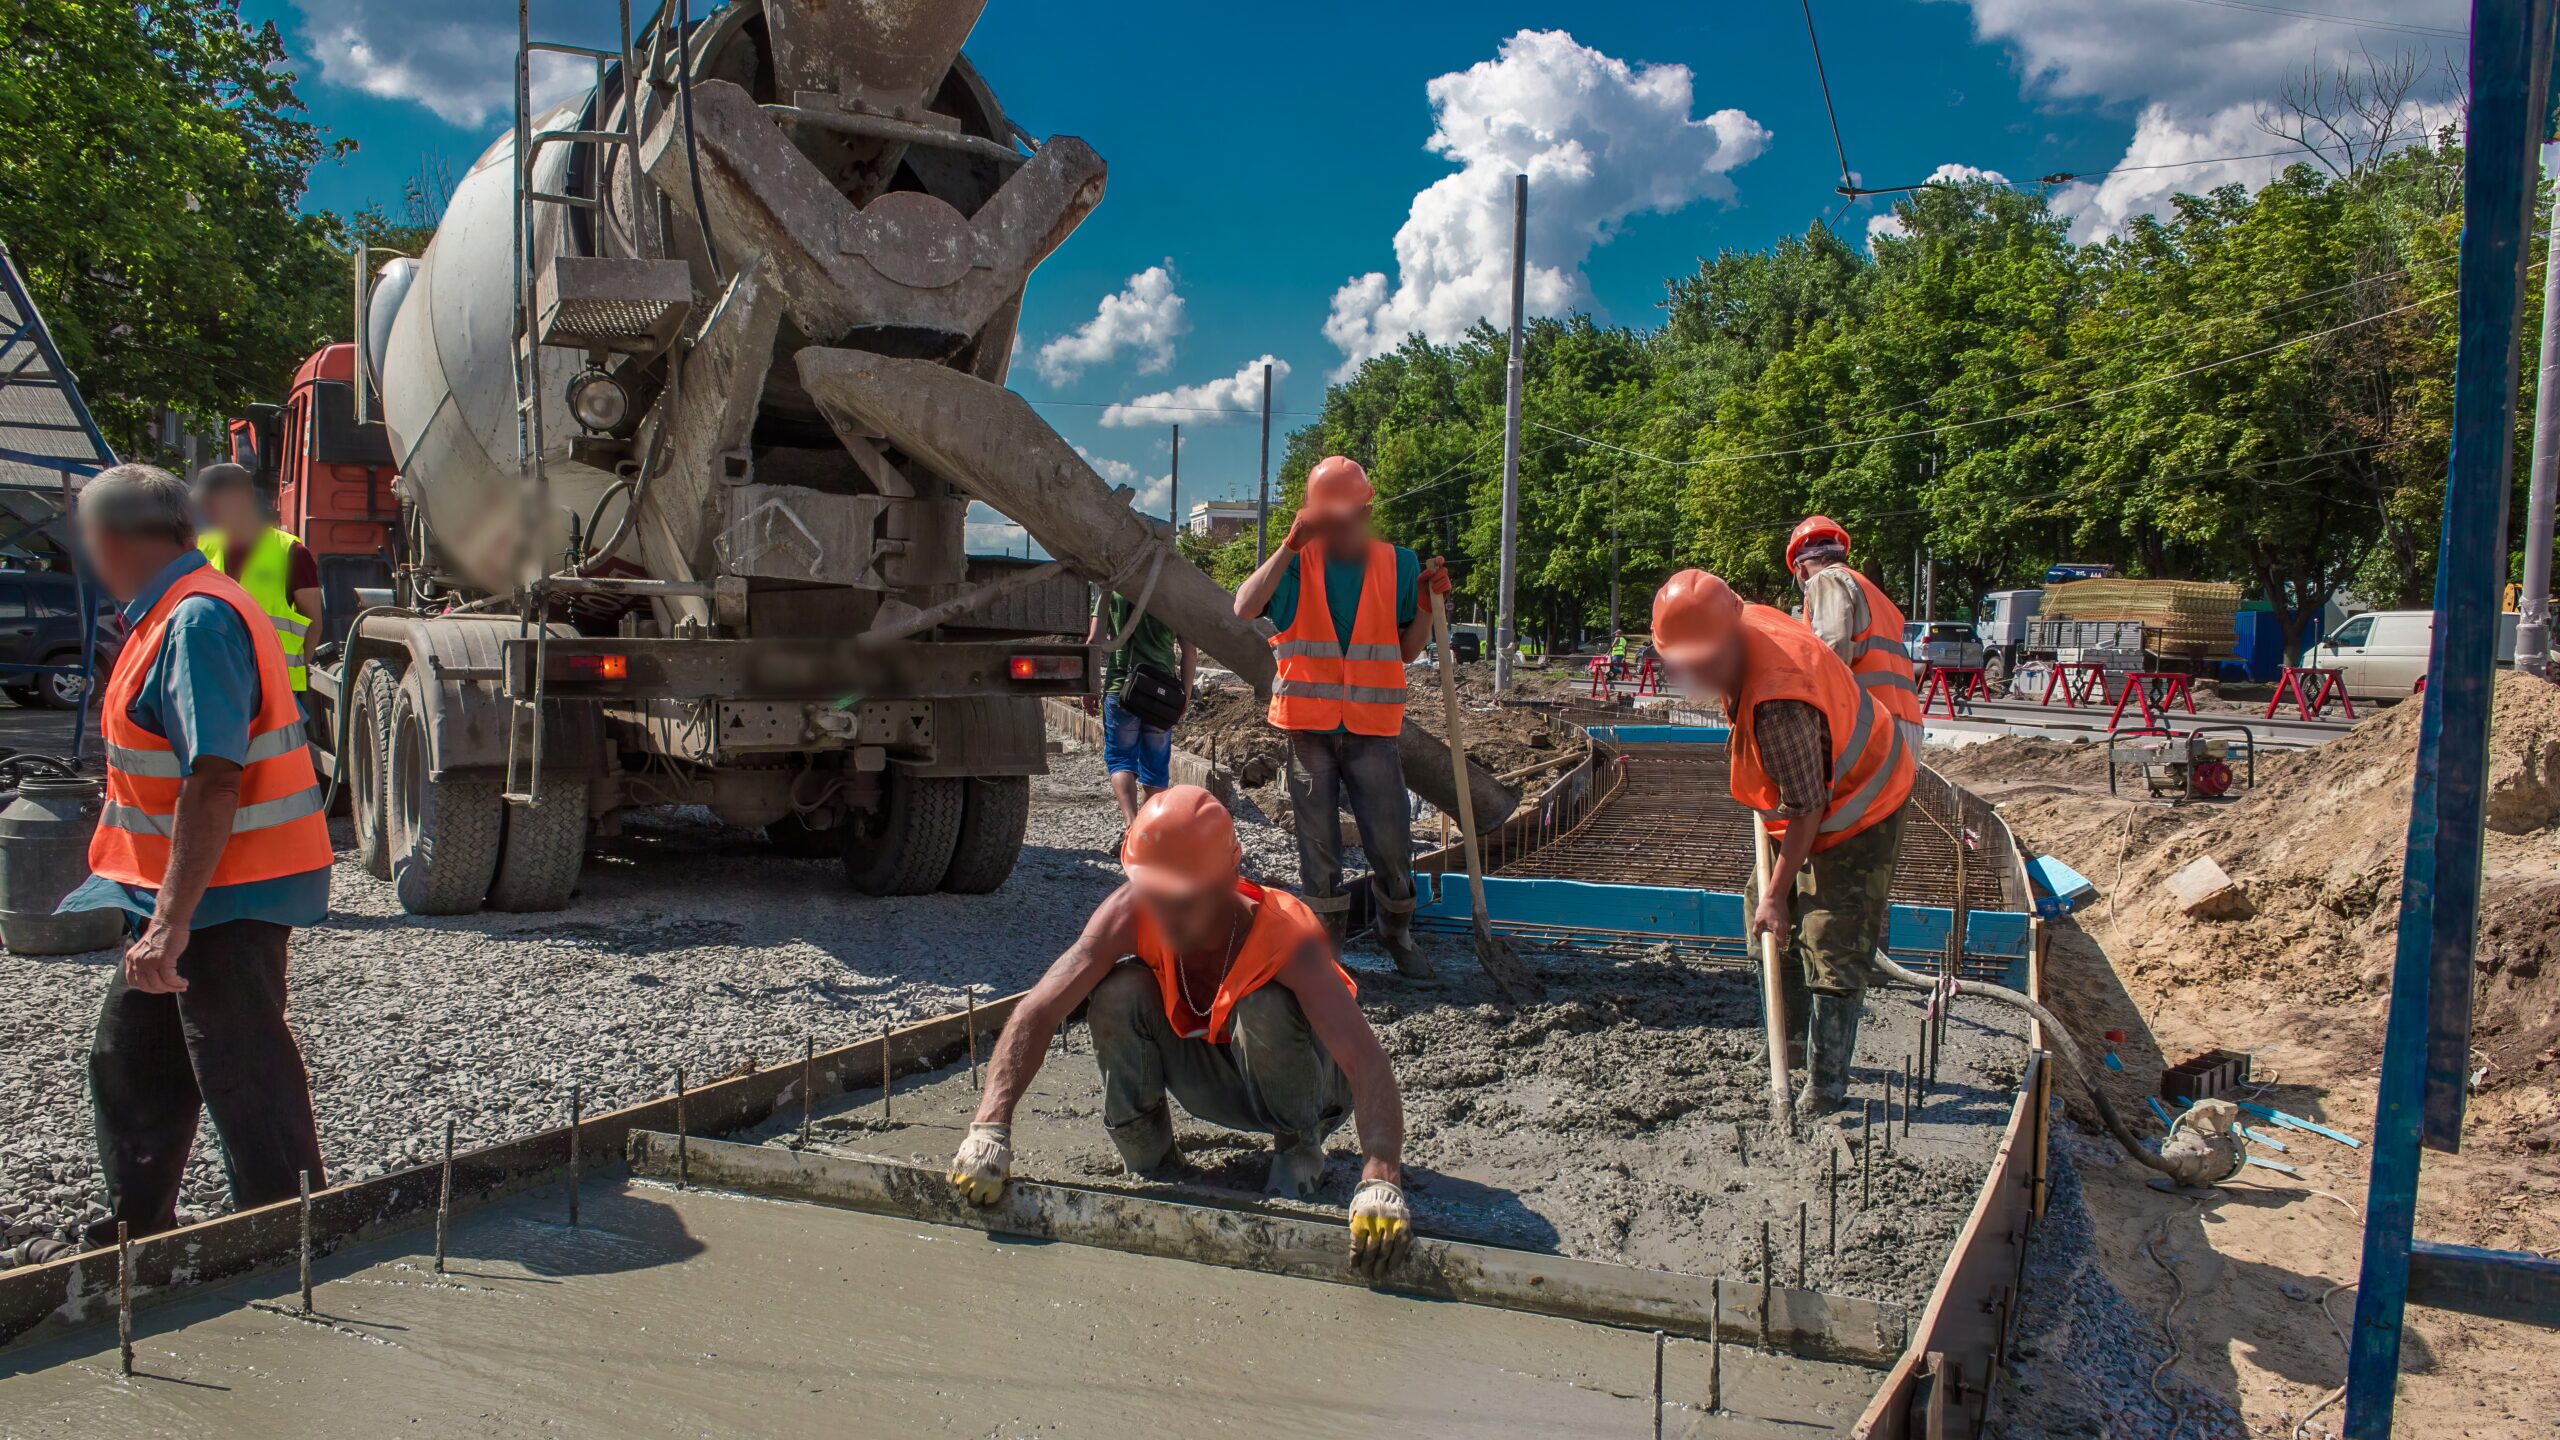
When municipal employees perform construction, maintenance, or rehabilitation work directly, the cost question becomes more detailed than “what is payroll?” A useful forecast should consider the direct crew, fringe and burden, indirect operations, general administration, support labor, materials, subcontractors, and other project inputs.
BreakEven+™ connects that financial foundation to estimating. Quantities and production assumptions can generate labor-hour requirements, while project inputs remain tied to the same forecast structure. This gives public managers another lens for developing budget scenarios, examining internal work plans, or comparing the economics of different delivery approaches without reducing everything to a single markup.
A wage rate alone does not show the full planning cost of municipal work. This example shows how direct wages, fringe, overhead, administration, and support can build into a fully supported hourly planning rate.
| Forecast component | Illustrative value |
|---|---|
| Direct base wages | $1,420,000 |
| Fringe / payroll burden | $548,000 |
| Department overhead pool | $686,000 |
| General administration pool | $392,000 |
| Support labor / operations | $244,000 |
| Total modeled labor & indirect structure | $3,290,000 |
Illustrative values are not municipal benchmarks, incurred-cost results, accounting guidance, or recommended rates. Actual configuration depends on the entity's own budgets, labor, allocation methodology, policies, and financial records.
Seeing these pools independently matters because a change in productive hours, staffing, benefits, supervision, or administrative cost can alter the amount that each productive hour must support. A forward model makes those relationships easier to test before a budget is locked.
BreakEven+™ can give finance, public works, utility, engineering, and department leadership a common financial structure for discussing how planned work consumes labor and support resources.
That distinction can make budget conversations more useful. Management can see whether a project assumption is being driven by wage mix, benefit cost, productive hours, departmental overhead, general administration, support labor, pass-through inputs, or production requirements.
FALIB® organizes forecast, pricing, production, and project-level information into connected reports. Municipal users can choose the level of detail that matches the way their labor and budget information is managed.
Build a detailed forward cost foundation when employee-specific wages, fringe, classifications, or labor assumptions need greater precision.
Explore FALIB®-Mr →Model labor by department, role, crew, classification, or other strategic grouping when employee-level detail is not required.
Explore FALIB®-Sr →Carry the originating rate structure into a specific estimate or change so the project-level financial result remains explainable.
Explore FALIB®-Jr →Show quantities, methods, production, labor hours, cost, unit rates, materials, and pricing detail behind the planned work.
Explore FALIB® P&P →Create a new versioned financial summary from accepted estimates and changes while keeping the source records intact.
Explore FALIB® Roll-Up →FALIB® distinguishes cost pools from the base used to allocate them. A department can model operational overhead separately from broader general and administrative costs, then use the configured allocation logic to understand how much support the forecast direct activity must carry.
This is useful when a municipality is trying to understand the full planning cost of an internal crew. A direct employee may spend the day paving, repairing a water line, operating treatment equipment, forming concrete, or maintaining a facility, while other employees and costs support that work indirectly. The forecast can preserve that distinction instead of treating every dollar as direct project labor.
The same annual labor and indirect-cost structure can produce a different planning rate when the number of productive hours changes. Vacation, training, administrative time, seasonal schedules, staffing vacancies, or non-project activity can all affect how much productive work is available to carry the forecast cost structure.
BreakEven+™ makes that relationship visible so users can test assumptions rather than relying on a static historical rate. The purpose is not to declare one rate correct for every municipal use; it is to give the organization a transparent model built from its own assumptions.
No. BreakEven+™ is a cost intelligence, forecasting, estimating, and reporting platform. It can complement an accounting, ERP, budgeting, or financial-management system by providing a forward-looking model for labor, indirect costs, project assumptions, and pricing or cost-recovery analysis.
Yes. FALIB®-Mr supports employee-level forecasting, while FALIB®-Sr supports grouped labor structures. A municipality can use the approach that best matches its available data and planning requirements.
Yes. The model can distinguish operational or departmental overhead from broader G&A and other configured cost categories. The purpose is to make the cost structure and allocation logic easier to understand rather than collapsing everything into a single unexplained percentage.
It can support project and program planning by connecting forecast labor and indirect-cost assumptions to quantities, production, labor hours, materials, subcontractors, support labor, ODCs, and other estimate inputs. The resulting outputs are forecasts based on user-entered or configured assumptions.
No. FALIB® is a forecasting and reporting framework. It can help users develop, test, explain, and document cost assumptions, but it does not replace statutory budgeting requirements, accounting records, procurement rules, or other governmental financial procedures.
Yes, provided each department is configured around the appropriate labor, productive hours, pools, allocation assumptions, and project inputs. The value of the model is that different operating units can use a consistent framework while retaining their own financial assumptions.
Forecast the labor. Organize the indirect pools. Understand the administrative load. Estimate the work. Then document the assumptions with FALIB® reporting.
Forecast outputs are based on assumptions and data entered or configured by the end user. They are not incurred-cost actuals, audited results, legal or accounting advice, or guaranteed financial outcomes.