BreakEven+™ for Municipal Capital Projects & Infrastructure

Build infrastructure budgets from the work, labor, and resources the project is expected to require.

BreakEven+™ helps municipalities forecast internal labor, fringe, overhead, G&A, support labor, materials, subcontractors, and other project inputs before a capital budget or project estimate is committed.
Capital PlanningInfrastructure ProjectsSelf-Performed + Contracted Work
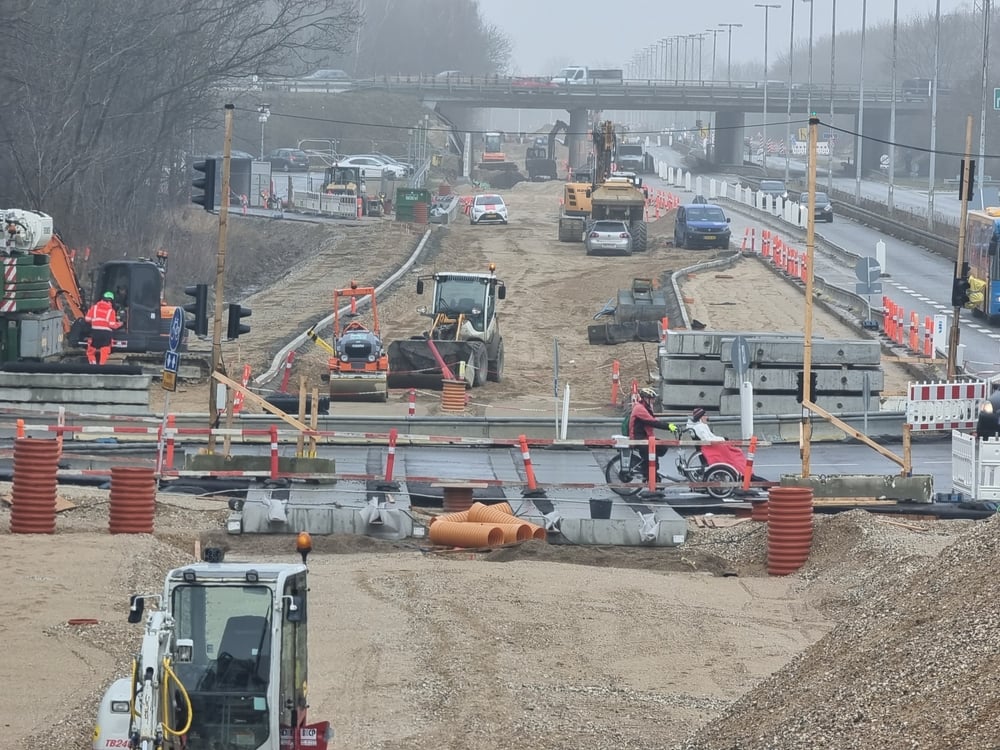
Municipal capital road and infrastructure construction representing BreakEven+ cost intelligence
Capital projects need more than a top-line number

Keep the municipality’s own labor and support structure visible beside outside project costs.

A capital project may combine municipal employees, engineering, inspection, project management, materials, equipment-related costs, contractors, subcontractors, and administrative support. BreakEven+™ helps keep those elements distinguishable.

One project can include both internal and external cost structures.

FALIB® can help show what the municipality expects to perform internally, what is purchased externally, and how the support structure contributes to the total project requirement.

Internal labor + indirect pools + project inputs + outside vendors.
Build the capital estimate in layers

Move from planned scope to a more explainable project budget.

01

Internal labor

Engineering, inspection, project management, field crews, technicians, and other municipal employees assigned to the project.

02

Indirect support

Fringe, supervision, facilities, administration, systems, G&A, and other support resources behind the work.

03

Materials & project inputs

Concrete, asphalt, pipe, coatings, equipment-related inputs, ODCs, quantities, and production assumptions.

04

Contracted portions

Prime contractors, specialty subcontractors, consultants, testing, or other outside project costs kept separately visible.

ScopeDefine the work and planned quantities.
HoursEstimate internal labor and support effort.
IndirectsApply the municipality’s configured cost structure.
Project InputsAdd materials, ODCs, and outside vendors.
BudgetProduce an explainable project requirement.
Illustrative capital project model

See how internal labor and outside project costs can coexist in one forecast.

The example below is illustrative only. It shows one way a municipality could structure an infrastructure project that includes internal labor and support as well as materials and contracted work.

$0.00Illustrative direct municipal labor mix per productive hour
$0.00Illustrative fringe and payroll burden per hour
$0.00Illustrative overhead and support allocation per hour
$0.00Illustrative fully supported internal planning rate
Illustrative infrastructure project budget $0.00M

Keep municipal labor and indirect costs separate from materials, subcontractors, consultants, and other externally purchased portions of the project.

Budgeted Internal Direct Hours0Illustrative engineering, inspection, project-management, and field hours charged directly to the project.
Budgeted Support / Indirect Hours0Illustrative supervision, administration, and other support labor associated with the capital program.
Internal direct labor$759K
Fringe / burden$302K
Overhead / G&A / support$548K
Materials & direct project inputs$1.24M
Contractors / subcontractors$4.00M

Illustrative values are not municipal benchmarks, accounting guidance, engineering estimates, or recommended rates. Actual configuration depends on the municipality’s own labor, indirect-cost methodology, project scope, procurement approach, financial records, and estimating practices.
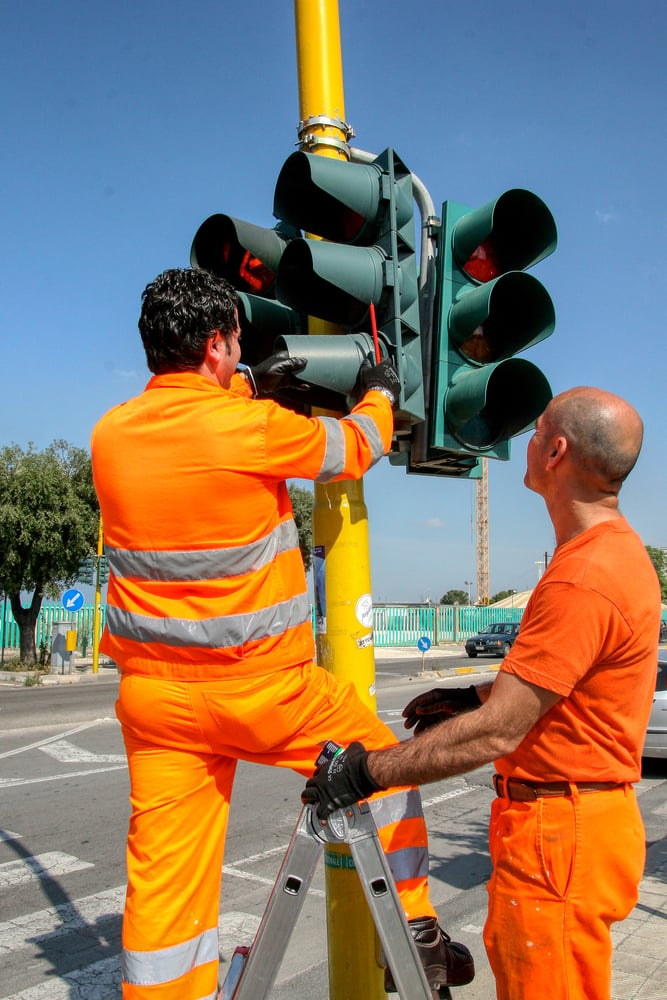
Municipal workers servicing traffic signal infrastructure representing internal labor and capital project support
Self-performed portions still matter

Do not lose the municipality’s own project labor inside the contractor total.

Even when a large portion of a capital project is contracted out, municipal employees may still perform inspection, engineering, project management, traffic-signal work, utility support, site coordination, punch-list items, or other project tasks.

  • Forecast internal direct hours separately from outside contract value.
  • Carry fringe, overhead, G&A, and support labor into the internal cost structure.
  • Add materials, subcontractors, ODCs, and other project inputs separately.
  • Keep change activity tied back to the project forecast.
  • Use FALIB® reporting to explain how the total project requirement was assembled.
Capital project use cases

Use the same cost-intelligence framework across different types of municipal infrastructure work.

Utility infrastructure

Capital planning also extends below the street.

Water mains, utility replacements, valves, piping, excavation, and related civil work can combine internal municipal labor and oversight with purchased materials and outside construction.
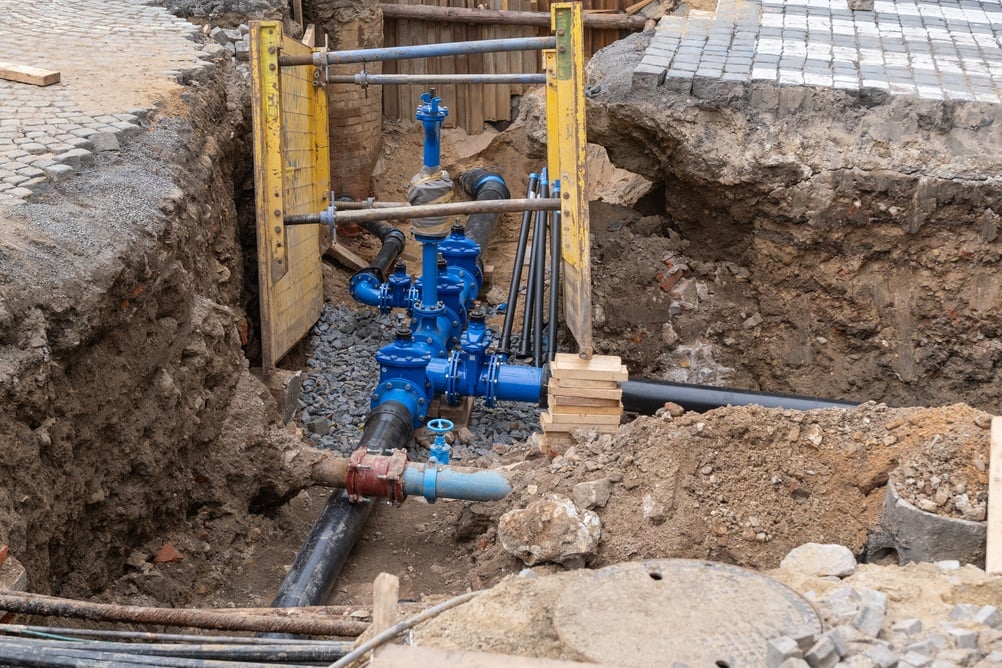
Municipal underground utility infrastructure project representing water and utility capital planning
Road & bridge rehabilitationCombine internal project labor, materials, contractors, inspection, support, and other project inputs.
Water & wastewater upgradesForecast municipal engineering and support beside equipment, construction, contractors, and other capital costs.
Municipal buildings & facilitiesTrack internal project management, support labor, materials, vendors, and construction-related costs.
Concrete & site improvementsEstimate self-performed concrete or site work separately from subcontracted portions of the project.
Drainage & stormwater projectsConnect field labor, materials, support, contractors, and project-management effort to the capital estimate.
Multi-year capital programsKeep assumptions organized across projects while preserving the cost foundation behind each estimate.
Internal and external costs belong in different lanes

Keep self-performed municipal effort distinct from purchased construction and professional services.

Municipality performs part of the work

Forecast internal engineers, inspectors, project managers, crews, supervision, support labor, fringe, overhead, G&A, and direct project inputs using the municipality’s own cost structure.

Outside firms perform part of the work

Keep contractor, subcontractor, consultant, testing, equipment, and other external costs separately visible rather than blending them into the municipal labor structure.

FALIB® Reporting

Carry the capital-project cost foundation from forecast to project detail.

FALIB® connects labor and indirect-cost assumptions to project, production, and consolidated reporting so the municipality can preserve the logic behind a capital estimate as the project develops.

Employee-level foundation

FALIB®-Mr

Use employee-specific wages, fringe, classifications, and labor assumptions when detailed internal labor is needed.

Explore FALIB®-Mr →
Grouped foundation

FALIB®-Sr

Model labor by crew, role, department, engineering group, or other strategic grouping.

Explore FALIB®-Sr →
Project view

FALIB®-Jr

Carry the originating cost structure into a specific capital estimate, project, or change.

Explore FALIB®-Jr →
Production detail

FALIB® P&P

Show labor hours, production, quantities, materials, cost, unit rates, and other project detail.

Explore FALIB® P&P →
Consolidated view

FALIB® Roll-Up

Bring accepted estimates and changes into a summarized financial view while keeping the supporting project records intact.

Explore FALIB® Roll-Up →
BreakEven+™ by SERVVIAN®

Give municipal capital projects a clearer internal and external cost foundation.

Forecast the municipality’s own labor. Separate the indirect pools. Add materials and outside project costs. Then use FALIB® reporting to explain how the capital requirement was built.